Spain's Beckham Law in 2026: 24% flat on first €600K of Spanish-source income, six-year window, and the 6-month election deadline most movers miss
⚖️ What the Beckham Law Actually Does in 2026
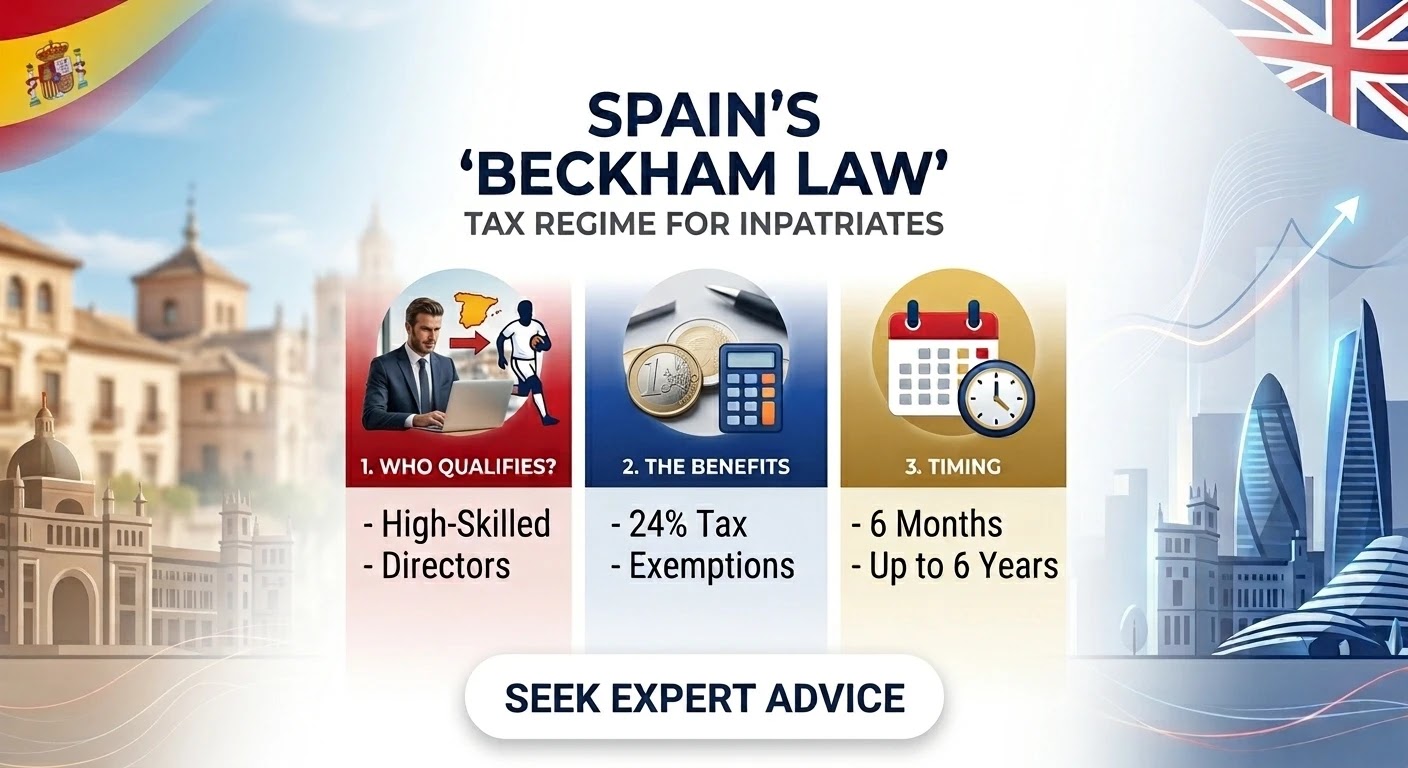
Spain's impatriate regime — informally called the Beckham Law after David Beckham's 2003 transfer to Real Madrid — lets qualifying newcomers elect a flat 24% rate on Spanish-source employment income, capped at a six-year window. The regime appears in Article 93 of the Ley del IRPF (formerly Article 35.4, consolidated in 2015 and reformed by RD-L 6/2023). It is the most generous personal income tax concession Spain offers non-resident workers in 2026 — and the most consistently missed.
The mechanics are simple. A worker who elects Beckham pays a flat 24% on the first €600,000 of Spanish-source employment income in any tax year the regime is active. Above €600,000, the standard progressive national rates apply (up to the 47% top marginal rate in 2026). The election lasts six tax years. After year six, the worker falls back to the standard LIRPF progressive scale (19-47%) without the option to re-elect. Beckham is employment-only: dividends (19%), interest (19%), capital gains (19%), rental income (24% non-EU or 19% EU with election), and Spanish-source passive income follow the LIRNR rates regardless of whether the regime is active. The only route into the regime is filing Modelo 149 with the Agencia Tributaria within six months of the trigger date — the date that varies by candidate profile and is the main reason most movers miss the window.
The €610K figure in the lead reflects a flat €500K salary across all six Beckham years. Most HNW movers see 3-4% annual raises, which pushes the cumulative saving toward €745K by year six. The exact number depends on salary progression, foreign-source passive income treatment, and whether the worker uses the Andalucía regional rebate on the portion of the tax bill that does not fall under Beckham. Three additional points matter before you file:
🌐 Who Qualifies in 2026 — and Who Doesn't
Eligibility is narrower than most tax-planning websites suggest. The regime is built for two distinct categories of mover: those relocating from a non-EU jurisdiction for a specific work-related reason, and certain Spanish nationals returning home after a foreign assignment. Below is the 2026 eligibility matrix that the AEAT and the Dirección General de Tributos use when ruling on Modelo 149 elections.
The "5 years prior" test disqualifies more applicants than any other criterion. A French banking executive who moved to Madrid in 2022 and now wants to switch employers in 2026 does not qualify for Beckham on the new contract — the 5-year clock has not yet expired. A German tech lead who arrived on a Blue Card in 2021 and wants to re-elect after five full years does qualify. The clock starts the day the Social Security alta registers you in Spain, not the day the work visa is granted and not the day the contract is countersigned.
A separate clarification: the Beckham regime is for employment income only. The Digital Nomad Visa (Ley 28/2022) is sometimes mistakenly treated as a Beckham sibling, but the DNV itself is a residency permit — Beckham is the tax election that a DNV holder must file separately. A DNV holder who forgets to file Modelo 149 within six months of arrival still ends up in LIRPF progressive (19-47%) by default. The DNV gives the right to elect; it does not auto-elect.
⏱️ The 6-Month Election Deadline — Why Most Expats Miss It
The election is irrevocable. Once you file Modelo 149, you stay in the regime for the full six years — you cannot opt out mid-cycle if the Spanish economy contracts, if you switch employers, if you take a sabbatical, or if you decide to leave Spain. The irreversibility is why most professional advisers recommend filing as soon as the contract is signed rather than waiting for the deal to "settle down".
The 6-month deadline is calculated from a trigger date that depends on the qualifying category. Getting the trigger date wrong costs the worker the regime for the full six-year cycle — there is no late-filing remedy, no penalty cure, no Ley General Tributaria Art. 119 extemporaneous path for Beckham. Below is the deadline matrix the AEAT applies.
💼 Worked Example — €500,000 Senior Executive Moving from London to Marbella in 2026
A senior investment-banking executive earning a £425,000 GBP base (approximately €500,000) leaves London in early 2026 to take a position at a Marbella-based family office. She has a Spanish employment contract with Social Security alta on January 15, 2026. She elects Beckham (files Modelo 149) on February 28, 2026 — well within the six-month window. The annual tax comparison is set out below.
The headline €610K figure used in the lead reflects the flat-€500K conservative path; the €675K figure with 3% salary growth tracks the more common HNW mover profile. Both numbers are illustrative — actual savings depend on the exact salary progression, on the Spain-UK double-taxation treaty application to Spanish-source income that is also taxed in the home country, and on whether the worker has investment income that stays outside the regime.
Three caveats the table does not show: (1) the executive does not save on Spanish-source passive income — rental income from a London property held through a Spanish-resident holding company is taxed at 24% under LIRNR regardless of Beckham; (2) the Beckham regime does not reduce capital gains tax on selling a Spanish property (19% with optional EU election to LIRPF progressive); (3) Beckham is incompatible with family wealth-tax avoidance strategies — Modelo 714 still applies on worldwide assets above the €2M threshold, and the Andalucía regional rebate applies to the wealth-tax bill but not to the income-tax bill Beckham replaces.
⚠️ Five Beckham Pitfalls That Catch HNW Movers in 2026
Pitfall 1: Triggering Spanish tax residency on the contract signing date (when the trigger is alta in Social Security)
Many HNW movers fix the dates wrong. The Beckham election clock starts on the Social Security alta date, not the contract signing date. A May 2025 contract with an October 2025 alta gives six months from October, not from May. Workers who rely on the May date and file Modelo 149 in late December get their filing refused as late, lose Beckham entirely, and have to wait for a new five-year foreign stint before another chance. The high-cost fix is annual tax-bill reconciliation across six years.
Pitfall 2: Claiming 24% flat on Spanish-source investment income
A common misunderstanding: "I elected Beckham, so all Spanish-source income gets 24%". The regime applies only to Spanish-source employment income. Dividends, rental income, capital gains from Spanish real estate, and bank interest are taxed at LIRNR rates (19% / 24% / 28%) regardless of Beckham. Spanish-source investment income must still be declared on Modelo 100 (after Beckham turns the worker into a resident) or Modelo 210 (if the worker stays LIRNR on passive income using the "split-year" election under Art. 24 LIRNR).
Pitfall 3: Defaulting to Modelo 210 quarterly, when Beckham requires Modelo 100 annual
Beckham converts the worker into a Spanish personal income tax (PIT) taxpayer. PIT filers use Modelo 100 — the annual form filed between April and June of the year following the tax year. Workers who default to the non-resident Modelo 210 quarterly model pay 24% withholding, miss PIT-specific deductions (investment fund contributions, pension plans up to €1,500/year, mortgage interest on a Spanish primary residence), and double-pay on income already taxed in the home country through the Spain-UK or Spain-US double-taxation treaty.
Pitfall 4: Forfeiting Spanish tax residency by leaving >183 days
Beckham requires the worker to keep Spanish tax residency throughout the six-year cycle. A HNW mover who keeps her primary residence in Marbella but spends 250+ days a year at a London office forfeits Spanish tax residency, and the Beckham regime collapses mid-cycle. Spain applies the 183-day rule strictly; the Dirección General de Tributos treats anyone present for 183+ days in a calendar year as Spanish tax resident. Some HNW movers keep the regime by limiting non-Spanish days to under 183 and maintaining a Spanish driver's license, healthcare card, empadronamiento, and Spanish bank account.
Pitfall 5: Assuming Beckham covers capital gains on Spanish property sales
Spain taxes capital gains on real estate at 19% (with the EU election to LIRPF progressive scale possible — most HNW movers pay the 19% flat). Beckham does not apply to capital gains even when the property is owned by the person who elected the regime. A homeowner selling a €1.5M Marbella villa five years into Beckham pays 19% on the gain regardless of the flat-rate election. The capital gain calculation uses the cadastral reference value (valor catastral) at acquisition and at sale, not the negotiated purchase price — a 2026 sale of a 2014 acquisition typically applies a 2% annual inflation adjustment.
- Spanish employment contract in hand, with the Social Security alta date identified
- Prior-residency test verified: 5-year foreign-residency gap confirmed by a tax-residency certificate (Modelo C14 or the equivalent from the previous country)
- Modelo 149 drafted by a Spanish tax adviser (not HR) within six months of alta
- Modelo 100 (annual PIT) registered with the AEAT, replacing the Modelo 210 quarterly default
- Modelo 714 provisional filing planned if worldwide assets exceed €2M
- Residency log in place: empadronamiento, Spanish driver's license, healthcare card, Spanish bank account — to defend the 183-day rule across the six-year cycle
- Six-year projection reviewed by an independent adviser with both Spanish and home-country cross-border experience
Spain's Beckham Law in 2026 is the single most generous personal-income-tax concession available to international executives relocating to the Costa del Sol. The regime turns a €500,000-a-year salary from a 44% effective rate under LIRPF progressive into a flat 24% — a cumulative six-year saving of €610,000 to €675,000 for most HNW mover profiles. The catch is the six-month election window (Modelo 149), which is the same window most expats blow without realising. File the election on day one of the Social Security alta, pair it with an independent cross-border tax adviser, and the regime delivers one of the cleanest six-figure tax wins available in Western Europe in 2026. Miss the window and the €610,000 saving collapses to a €0 saving — re-electing requires another full five-year foreign stint.
📞 +34 624 770 233 · WhatsApp · 📧 info@cerealestates.com
🌐 Request a Property Consultation
Ready for the lifestyle?
Download our exclusive free guides to learn everything about living and investing in Spain.
Explore Expert Guides
